01522 710 860Let’s talk property

THE DETAIL, AT YOUR OWN PACE

Your property investor guide.
Start with the questions that matter.

A useful investment conversation starts with understanding the process, the numbers and your own priorities. Use this guide alongside the Oakridge investor pack.

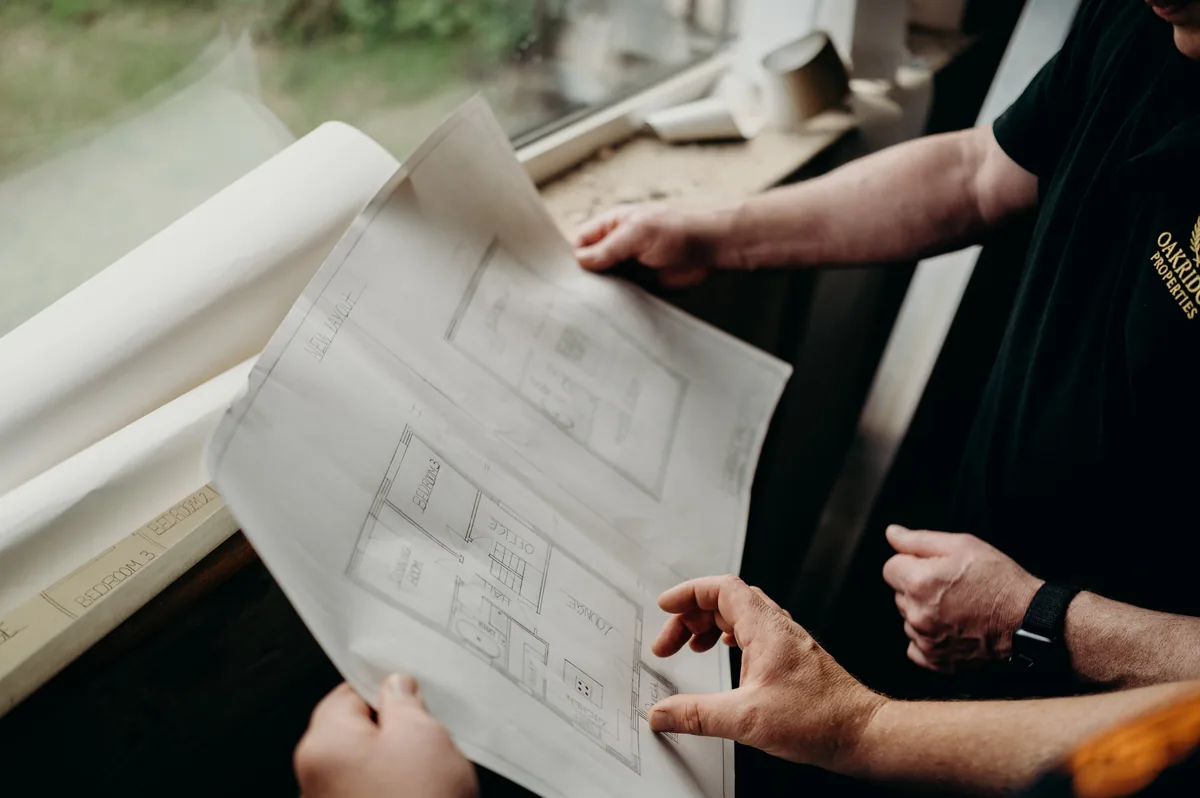
Oakridge team reviewing the detail of a property plan

Download the original investor pack

The Oakridge brochure introduces the team, our property approach and the investment journey. The download retains the original investor pack with its updated website cover.

Download the investor pack ↓

Read the PDF in your browser. Brochure examples provide context; the documents and figures agreed for a specific project determine that arrangement.

Available capital and the total project cost

Your available capital is the money you can consider committing after allowing for your other needs. Total project cost includes the acquisition, works and wider costs through to exit. Where borrowing is proposed, investor capital and finance are separate parts of that funding plan.

Conversations can begin from £50,000 of available capital. The amount a particular opportunity requires depends on the property and structure. It is important to discuss whether you may need access to those funds, because property cannot usually be converted into cash quickly.

Understand the words behind the numbers

  • Refurbishment budget: the allowance for the agreed works, labour and materials.
  • Contingency: an allowance for unexpected work, rather than an extra profit margin.
  • Holding costs: costs incurred while the property is owned, including relevant finance, insurance and utilities.
  • Exit: the intended sale or other agreed route at the end of the project.
  • Project profit: proceeds less the costs included in the calculation; tax and the allocation between parties must be checked separately.

Questions to ask before committing

  • Who owns the property, and what exactly am I investing in?
  • What fees, finance costs and taxes apply to me?
  • Which figures are estimates, and what evidence supports the resale assumption?
  • What happens if costs rise or the sale takes longer?
  • What approvals, updates and contractual rights will I have?
  • How and when are proceeds distributed?

Ask your solicitor, tax adviser or financial adviser to assess the proposed arrangement for your circumstances. Do not assume that regulation or compensation protection applies simply because the underlying asset is property.

Compare objectives before comparing returns

A refurbishment for resale and a retained rental property are different plans. One depends on delivering a sale; the other also requires consideration of letting, management, maintenance, compliance and periods without a tenant. Neither is a universal fit.

Read our buy–refurbish–sell guide for project budgeting and our hands-off investment page for the support and decisions involved. Then bring your questions to the team.
THE DETAIL, AT YOUR OWN PACE

Start with the
investor pack.

For professionals and business owners considering a hands-free approach to Lincolnshire property.

  • Our team and local approach
  • The investment journey and your role
  • Property criteria and example numbers
  • Questions to discuss before committing

Original Oakridge investor pack with its new website cover · PDF.

Oakridge investor packYOUR CAPITAL. OUR PROPERTY EXPERTISE.

A REASON TO MAKE A PLAN

Your savings may be
losing buying power.

A £75,000 bank balance can still say £75,000 while buying less each year.

If inflation runs ahead of the interest your savings earn, the real value falls. That is a reason to consider your options carefully. Property is one possible route, with its own costs, uncertainty and need for a longer-term view.

Let’s talk about your objectives
SEE WHAT INFLATION COULD DO / 10 YEARS
Your £75,000 savings today£75,000
What that money could buy in 10 years£55,807

£19,193 less buying power at 3% annual inflation and 0% annual savings interest.

Same number in the account. Less spending power in the real world. Change the assumptions below to see the effect.

Constant rates, annual compounding, no tax, fees, deposits or withdrawals. This shows purchasing power in today’s money—not a prediction or a comparison of property returns. Interest can offset inflation. Property can fall in value and is less accessible than cash.

How inflation works — Bank of England

CONFIDENCE STARTS WITH CLARITY

Good questions.
Straight answers.

We would rather have a useful conversation than promise an outcome we cannot guarantee.

How much capital would I need?

Initial conversations can begin from £50,000 of available capital. The amount a particular project needs depends on the purchase, works, finance, ownership and exit plan. Our illustrations show different capital ranges and funding assumptions; they are examples, not minimum investment offers.

What does hands-free actually mean?

Oakridge coordinates sourcing, assessment, acquisition, refurbishment and the agreed exit or handover. We agree reporting and decision-making arrangements before proceeding. You decide whether to invest and remain involved in material decisions as set out in your agreement.

Is this a fixed-return investment?

No fixed return is offered by this website. The examples model property projects with profit dependent on the eventual sale price and costs. Any lending, finance or joint-venture arrangement requires separate project-specific terms and assessment.

Are my capital or returns guaranteed?

No. Values can fall, costs can rise and sales can take longer than expected. Property is not readily converted into cash. You could receive less than you invest. The legal structure determines your rights and protections; do not assume FCA regulation or FSCS protection applies.

How are fees and updates handled?

Scope, fees, funding, reporting frequency and responsibilities are agreed in writing for the individual project. The service-fee figures shown in our examples are modelling allowances, not a quotation. Ask us how your project would be structured.

What about rental income or retirement plans?

We can discuss a longer-term buy-to-let approach separately from a refurbishment for sale. It needs its own assessment of rent, finance, maintenance, compliance, management costs and potential void periods. Neither rental income nor future value is guaranteed.

What happens when I contact you?

We start with your objectives, available capital and timeframe, then arrange a suitable conversation. An enquiry is not a commitment to invest and does not automatically book a call. You can call us directly on 01522 710 860.

GOOD INTRODUCTIONS DESERVE A THANK YOU£500referral thank you

Know someone
who’d value our approach?

Once you’re an Oakridge investor, introduce a friend or family member who goes on to invest with us, and our referral scheme offers you a £500 thank you.

Ask us about making an introduction

Contact us first so we can confirm eligibility, the qualifying investment and payment timing in writing. Please get their permission before sharing anyone’s details. The referral thank you is separate from any investment return.

Your questions.
Our next conversation.

Talk through your objectives, capital and timeframe with the Oakridge team.

Arrange an investor conversation